1. Aareon is the consolidator, and its price is known
Aareon has bought six German vendors since 2021: wohnungshelden (August 2021) [1], GAP Group with the immotion ERP (October 2021) [2], KARTHAGO/UTS (2023) [3], Haufe-Lexware Real Estate (June 2024) [4], HausPerfekt (August 2024) [5] and easimo (May 2026) [6]. TPG and CDPQ bought Aareon itself in October 2024 at about €3.9 billion enterprise value [7]. That is 11.3 times its 2023 revenue of €344 million and 39 times its adjusted EBITDA of €100 million [8].
Among housing companies, Aareon dominates. In the 2024 survey of GdW member companies, 81.4% of those that named their ERP used an Aareon system; the next largest were ZHAUS with 4.4% and Hypoport’s WOWIPORT with 2.9% [9]. The next layer belongs to two listed groups, CHAPTERS Group with Win-CASA [10] and Hypoport with FIO SYSTEMS and WOWIPORT [11], and to the cooperative Hausbank München, which added HVW3 to its own imveon in 2024 [12].
2. 22 of the 57 vendors are owned by founders, families or managers
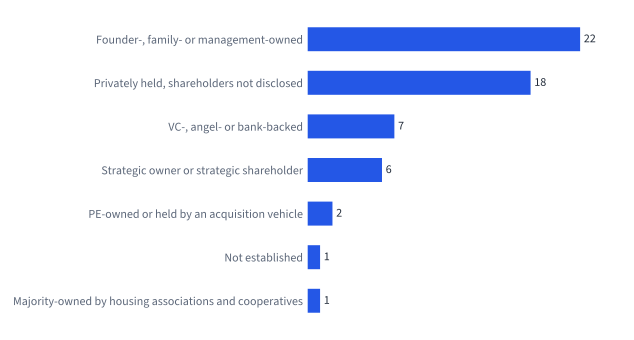
Of the 57 vendors in the census, 22 are owned by their founders, a family or their management. Only two belong to private equity or an acquisition vehicle: Aareon and Immoware24. A group counts once with its acquired brands.
| Owner type | Vendors | Share |
|---|---|---|
| Founder-, family- or management-owned | 22 | 39% |
| Privately held, shareholders not disclosed | 18 | 32% |
| Backed by venture investors, angels or a bank | 7 | 12% |
| Strategic owner or strategic shareholder | 6 | 11% |
| Private equity or an acquisition vehicle | 2 | 4% |
| Majority-owned by housing associations and cooperatives | 1 | 2% |
| Not established | 1 | 2% |
3. AI splits the field: 21 vendors have it in production, 29 show nothing
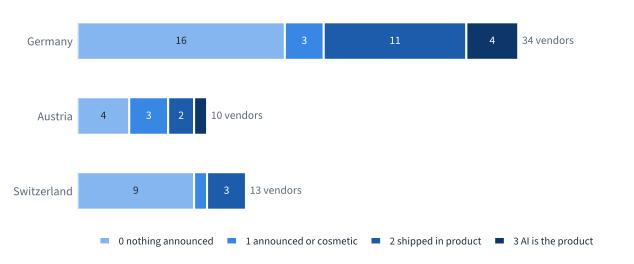
Every vendor is scored from 0 to 3 on dated public evidence. Five are AI-first: DoNexus, Verwalter.ai, Buzzard AI and Geniefy in Germany, and Cambioo in Austria. Sixteen have shipped AI inside an established product, among them Aareon, whose AAVA assistant for housing companies is live while KIAAN for property managers was in its final pilot in April 2026 [13]. Seven have announced AI without shipping it. Twenty-nine show nothing public, among them most long-established ERP vendors such as GFAD, Realax, PROMOS.GT, INtex, ALCO, ZHAUS, Abacus and Quorum. In Switzerland, 9 of 13 vendors score 0.
Succession deals usually come from the owner-run vendors. Of the 22 founder-, family- or management-owned vendors, 12 score 0. Six of the 22 were founded before 1990, and only one of those, DOMUS, has AI in its product.
| Score | Germany | Austria | Switzerland | Total |
|---|---|---|---|---|
| 3 · AI is the product | 4 | 1 | 0 | 5 |
| 2 · shipped inside the product | 11 | 2 | 3 | 16 |
| 1 · announced or cosmetic | 3 | 3 | 1 | 7 |
| 0 · nothing announced | 16 | 4 | 9 | 29 |
4. Twenty deals since 2019, and only two with a price
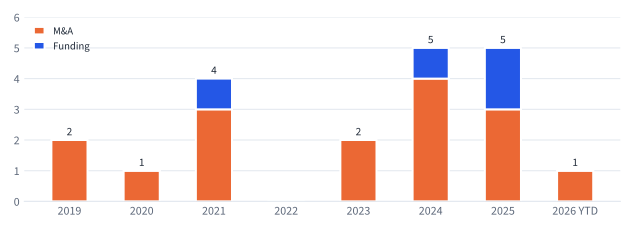
The report lists 20 transactions and funding rounds with a DACH target from 2019 to 2026: 13 control acquisitions, 3 minority stakes and 4 funding rounds. Two carry a price. Aareon was sold at 11.3 times its 2023 revenue [7][8]. For Immoware24, FCR Immobilien sold its 10% stake for €25.2 million in March 2025, which implies about €250 million for the equity [14]; the commercial register now shows an acquisition vehicle, Mountainview BidCo GmbH, as sole shareholder, and the investor behind it is not disclosed [15]. Immoware24 does not publish its revenue. On the report’s estimate of €6–10 million, the price is about 25–42 times revenue (confidence: low).
The older anchor is Hypoport’s purchase of FIO SYSTEMS in 2018 for about €70 million in cash and shares, about 10 times FIO’s 2017 revenue [11]. Market benchmarks for comparison: about 7.0 times ARR for public SaaS and 4.8–5.3 times for private SaaS [16], 10–14 times ARR for European vertical SaaS with strong growth and retention in 2025 [17], and about 8.5 times EBITDA for DACH small-cap software in Q3 2026 [18].
What the full report adds
- The census of all 57 vendors: HQ, founding year, owner, size signals, product scope and pricing.
- The AI-readiness matrix with the dated evidence and the source behind every score.
- An acquisition shortlist of seven candidates and a six-company watch list. Each profile gives the legal entity and register number, filed accounts where available, directors, register events, the evidence for and against, and a confidence level.
- All 20 deals with their terms, the valuation context and the risks an acquirer should watch.
- An Excel workbook with the 57 vendors and the 20 deals, a source URL on every row.
EUR 3,500 per organisation, next edition included. The report and the workbook are sent before you pay; the invoice follows with 14-day terms. Write “Please send” with your organisation’s name to [email protected].
Method and sources
The census was closed on 9 October 2026. It uses public sources only: commercial registers and filed accounts, company websites, press releases and trade press. A group counts once with its acquired brands. Adjacent companies are named in the report’s methodology but not counted: metering services, broker software, horizontal chatbot platforms, construction software and tech-enabled property managers. Estimates state their method and a confidence level.
- Aareon acquires 100% of wohnungshelden GmbH, 10 August 2021. aareon.de
- Aareon signs the acquisition of GAP Group (ERP immotion), 10 October 2021. vdwbayern.de
- Aareon acquisition of KARTHAGO/UTS, closed 1 February 2023. mergerlinks.com
- Aareon acquires Haufe-Lexware Real Estate, June 2024. haufegroup.com
- Aareon bought HausPerfekt in August 2024; HausPerfekt is now listed as an Aareon ERP product. haufe.de, aareon.de
- Grant Thornton advises Aareon on the acquisition of easimo, closed 21 May 2026. grantthornton.de
- Aareal Bank and Advent International sell Aareon to TPG for about €3.9 billion. lacaisse.com
- Aareal Bank Group Annual Report 2023, Group Management Report: Aareon revenue and adjusted EBITDA. aareal-bank.com
- GdW member survey on software use, 2024. gdw.de
- CHAPTERS Group AG Annual Report 2023: Software24.com GmbH (Win-CASA). chaptersgroup.com
- Hypoport acquires FIO SYSTEMS, 2018. cash-online.de, fio.de
- Hausbank München eG takes over Giesse + Partner Software (HVW3), April 2024. vdiv.de, imveon.de
- Aareon AI: AAVA and KIAAN. aareon.de
- FCR Immobilien AG ad-hoc release, 26 March 2025: sale of its 10% stake in Immoware24 GmbH for €25.2 million. fcr-immobilien.de
- Immoware24 GmbH, Amtsgericht Stendal HRB 19334: shareholder and filed accounts. handelsregister.ai
- SaaS Capital: private SaaS company valuations. saas-capital.com
- SaaS valuation multiples in Europe. masynergy.eu
- EBITDA multiples, DACH software. dealorigination.de